Deutsche Bank Analyst Boosts SiriusXM to 'Buy', Citing Undervalued Digital Audio and $45 Price Target
Introduction
As the summer season winds down, Wall Street analysts continue to monitor the media landscape, with one notable call emerging for satellite radio giant SiriusXM. Deutsche Bank analyst Bryan Kraft has issued a significant endorsement, upgrading his rating on SiriusXM to “buy” from “hold” and substantially increasing his price target to $45 per share, a considerable jump from the stock’s recent closing price of $29.77. This optimistic outlook is underpinned by Kraft’s conviction that the market is overlooking the substantial growth potential within SiriusXM’s digital audio advertising segment, particularly its strategic partnership with YouTube.
Key Details
- Analyst Upgrade: Deutsche Bank’s Bryan Kraft moved SiriusXM to “buy” from “hold”.
- Price Target Increase: Kraft raised his price target to $45 from $31.
- Undervalued Asset: Kraft believes SiriusXM’s digital audio advertising, especially its YouTube deal, is not fully appreciated by the market.
- Revenue Projections: The YouTube deal could generate $2 billion in annual incremental revenue by 2029.
- Company Guidance: SiriusXM raised its full-year guidance for revenue and EBITDA by $25 million in July.
- Conservative Estimates: Kraft views the company’s guidance as conservative and has increased his own forecasts.
- Shareholder Value: Berkshire Hathaway has been increasing its stake, potentially exceeding 50% due to share repurchases.
- Howard Stern Return: The analyst’s call did not directly mention the return of Howard Stern, but his presence remains a significant factor for the company.
Background
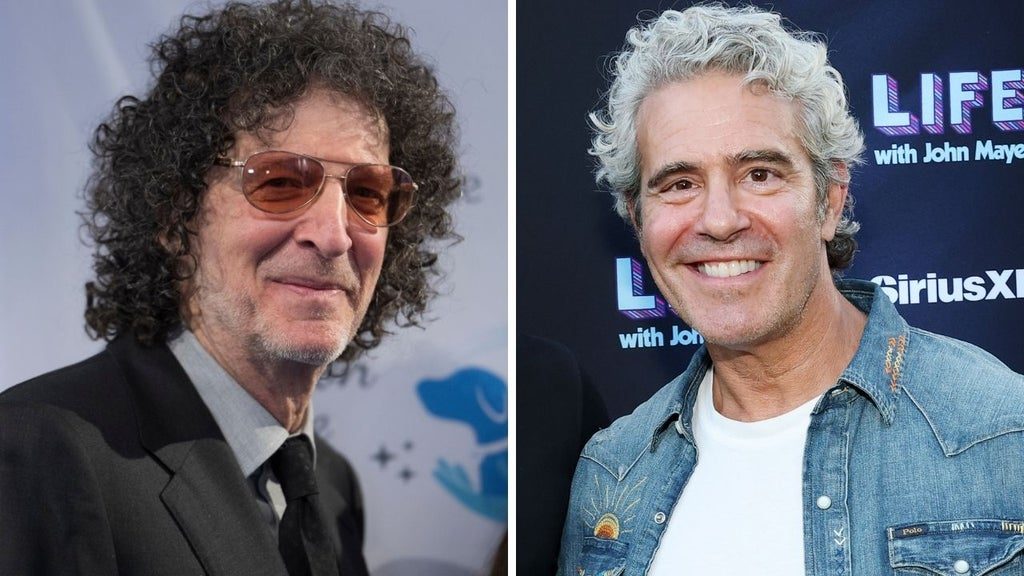
SiriusXM, a long-standing player in satellite radio, has been navigating a dynamic media environment. While its core subscription business remains a revenue anchor, the company has been actively seeking new avenues for growth. The recent announcement of Howard Stern’s return with a weekly show and video stream on HBO Max, alongside the reallocation of one of his former channels to Bravo host Andy Cohen, highlights the company’s efforts to retain and attract talent and diversify its content offerings. Concurrently, the company has been strategically expanding its advertising partnerships, notably securing exclusive U.S. audio advertising representation for YouTube. This move, along with an enhanced relationship with Amazon’s ad platform, signals a deliberate push into the burgeoning digital audio advertising market.
Impact Analysis
Kraft’s analysis hinges on the significant, yet seemingly disregarded, potential of SiriusXM’s advertising business. He projects that the exclusive deal with YouTube could unlock approximately $2 billion in annual incremental revenue by 2029, with high-teen margins. This alone could boost EBITDA by an estimated $350 million to $400 million. Furthermore, the expansion of its relationship with Amazon’s ad platform is expected to contribute additional advertising revenue. Kraft anticipates steady subscription revenue, bolstered by efforts to enhance subscriber value through companion subscriptions and expanded sports programming, with a price increase anticipated next year. The company’s own second-quarter earnings call revealed positive subscriber trends, including positive net additions, increased Average Revenue Per User (ARPU), and historically low churn rates. Kraft’s more bullish forecasts for 2026 revenue and EBITDA, exceeding the company’s raised guidance, underscore his confidence in these growth drivers.
“We believe SiriusXM is mispriced based on a large disconnect between consensus estimates and what we believe the company can achieve in 2027 and 2028,” Kraft stated in his report. “The opportunity is further enhanced by SiriusXM’s return to allocating capital toward share repurchases in the second half of 2026, as well as what we view as conservative 2026 guidance.”
Broader Context
Beyond its operational performance, Kraft points to SiriusXM’s valuable spectrum assets as an additional source of potential value. The Federal Communications Commission (FCC) may restructure certain unused spectrum bands, creating opportunities for SiriusXM to sell or lease these newly formed bands. Another significant development is the increasing stake held by Berkshire Hathaway. The investment conglomerate recently disclosed ownership of 37% of SiriusXM’s outstanding shares, a figure that could surpass 50% as SiriusXM continues its share repurchase program. Kraft acknowledges this concentration of ownership but views it as manageable, suggesting potential strategies for the board to address the threshold without jeopardizing the investment case.
Future Outlook
The upgrade from Deutsche Bank suggests a potentially brighter future for SiriusXM, driven by a dual strategy of solidifying its core subscription base while aggressively pursuing growth in digital advertising. The analyst’s confidence, reflected in his increased price target and forecasts, indicates that the market may soon re-evaluate SiriusXM’s valuation. The company’s focus on subscriber retention, ARPU growth, and the strategic exploitation of its advertising partnerships, particularly with YouTube and Amazon, are key elements to watch. Furthermore, the potential monetization of its spectrum assets and the evolving relationship with major shareholder Berkshire Hathaway add layers of intrigue to the company’s long-term prospects. If SiriusXM can successfully execute its advertising strategy and leverage its existing assets, Kraft’s $45 price target may prove attainable.
Conclusion
Deutsche Bank’s upgrade of SiriusXM to a “buy” rating, accompanied by a significant price target increase, signals a strong conviction in the company’s future performance. Analyst Bryan Kraft’s thesis centers on the market’s underestimation of SiriusXM’s digital audio advertising potential, particularly the lucrative partnership with YouTube. Coupled with steady subscription revenues, strategic capital allocation, and valuable spectrum assets, SiriusXM appears poised for growth. While challenges remain in the competitive media landscape, this Wall Street endorsement provides a compelling case for investors to reconsider the satellite radio provider.
Source: thewrap.com