Couple's Move-In Reveals Divergent Spending Priorities, Leading to New Financial Strategies
Introduction
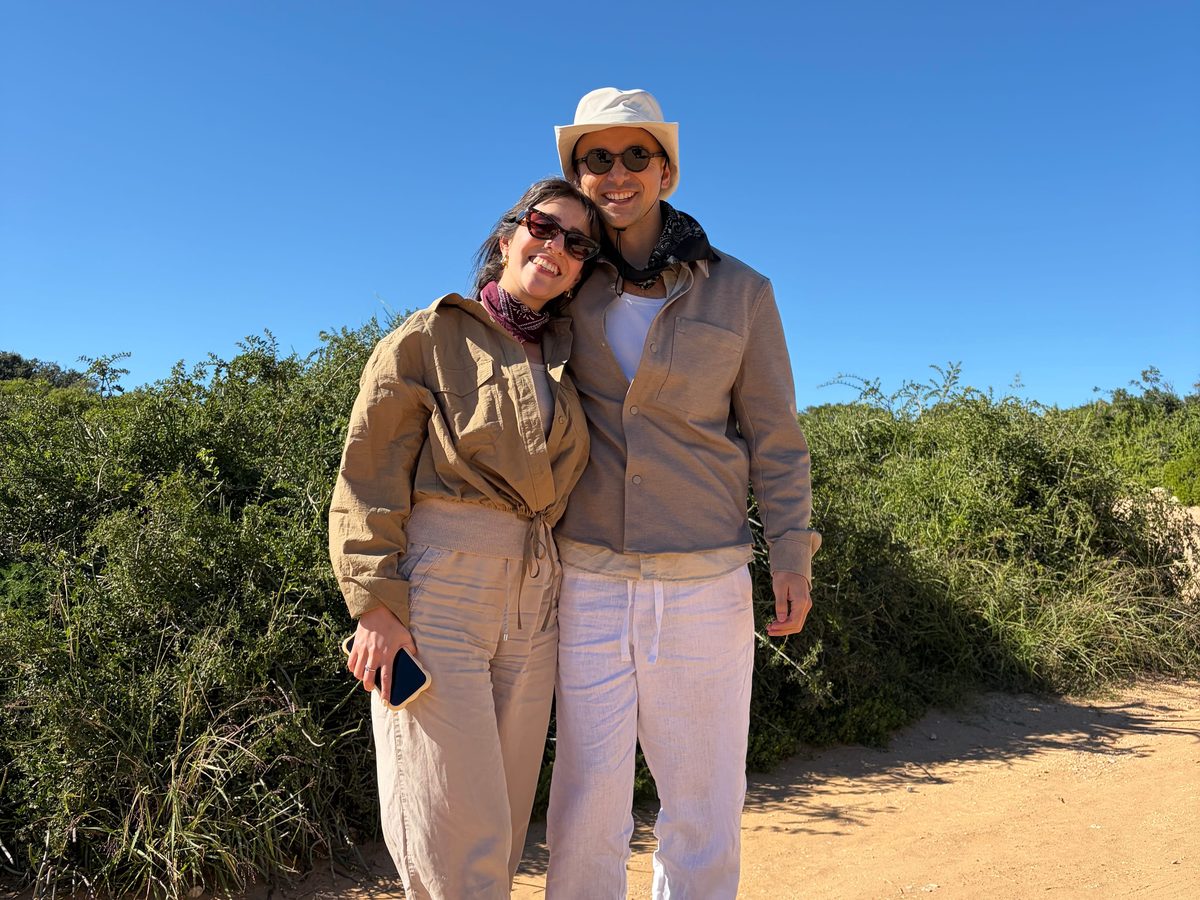
The transition from dating to cohabitation often brings to light subtle, yet significant, differences between partners. For one couple, this became particularly apparent when navigating their finances after moving in together. While they initially believed they were aligned on monetary matters, the shared reality of household expenses and lifestyle choices revealed distinct priorities, prompting a reevaluation of their financial strategy. This experience underscores a common challenge couples face: aligning individual spending desires with shared financial goals.
Key Details
- The couple, with similar backgrounds and incomes, initially adopted a 50/50 split for shared expenses like date nights and groceries.
- Moving in together highlighted a fundamental difference: one partner prioritized experiences and travel, while the other favored improving their daily living environment and home.
- This divergence led to friction, as the 50/50 model felt unfair when one partner funded something they didn't value.
- The couple developed a new system involving categorized spending: needs, individual priorities, and shared enjoyment.
- A joint savings account was established for shared goals and expenses like rent, while separate accounts manage personal priorities.
- They also moved towards dividing shared costs proportionally based on income, rather than a rigid 50/50 split.
- Flexibility and a willingness to compromise, rather than strict accounting, became central to their financial harmony.
Background
The author, having lived abroad for much of their financially independent life, had already questioned traditional relationship financial norms, such as the expectation for men to pay for everything. This personal journey of financial independence and cultural comparison set the stage for their relationship. Upon entering a serious partnership with someone who shared a similar background and international experience, the author was curious about their financial compatibility. Initially, their similar incomes and straightforward approach to splitting expenses seemed to indicate strong alignment. However, the decision to move in together acted as a catalyst, amplifying underlying differences in how they envisioned their money being used.
Impact Analysis
The shift from separate living to cohabitation significantly impacted the couple's financial dynamic. The initial 50/50 split, which felt equitable when applied to discretionary spending like date nights, became a source of contention when applied to larger, shared commitments like rent and home improvements. The partner who valued experiences felt that contributing equally to a more expensive apartment or home upgrades they didn't prioritize was unfair. Conversely, the partner who valued home comfort might have felt their desire for a nicer living space was being undervalued by the other's preference for immediate, experiential gratification. This tension highlighted that financial compatibility isn't just about income levels or spending habits, but about the underlying values and life goals that drive those habits. The realization that their core difference lay in what they wanted their money to *do* for them, rather than how much they earned or spent, was a critical turning point.
Broader Context
This couple's experience mirrors a common challenge in modern relationships. As societal norms around gender roles in finances evolve, and as individuals increasingly prioritize personal fulfillment and experiences, the potential for financial divergence grows. Unlike previous generations where traditional roles might have dictated spending patterns more rigidly, today's couples often grapple with aligning diverse personal aspirations. The rise of the "experience economy" further complicates this, with many valuing travel, dining, and activities over material possessions or home improvements. This case study illustrates that financial harmony in a partnership requires more than just equal contributions; it demands open communication, mutual understanding of differing priorities, and a flexible framework that accommodates individual desires within a shared life.
“Our main difference isn't how much we earn, or even how much we spend, but what we want our money to do for us.”
Future Outlook
Having navigated the complexities of shared living expenses, the couple is now better equipped to manage future financial decisions. Their established system of categorization, joint accounts for shared goals, and proportional contributions provides a solid foundation. The emphasis on flexibility and compromise over rigid adherence to rules suggests they are prepared for ongoing adjustments as their lives and priorities evolve. Their next shared project, acquiring a dog, signifies a commitment to building a shared future and applying their refined financial approach to new, common objectives. This proactive and adaptable strategy bodes well for their long-term financial and relational well-being.
Conclusion
The journey of this couple from a simple 50/50 split to a more sophisticated financial strategy demonstrates the importance of adapting financial plans to the realities of a shared life. By moving beyond a one-size-fits-all approach and embracing open communication, categorization of expenses, and proportional contributions, they successfully transformed potential conflict into a system that respects both individual desires and shared goals. Their experience serves as a valuable lesson for other couples: financial alignment is an ongoing process that requires understanding, flexibility, and a shared commitment to building a life together, one compromise at a time.
Source: businessinsider.com